Family Budget Basics: A Simple Monthly System for Two Busy Adults
A simple family budget needs one shared plan, a monthly 30-minute money meeting and automatic transfers. Steps, categories and fixes for two busy adults.
A simple family budget for two busy adults comes down to three habits: list all monthly income and bills in one shared place, give every dollar a job before the month starts, and meet for about 30 minutes once a month to check the numbers. Automatic transfers for bills and savings do most of the daily work, so neither partner has to track every purchase. The system below fits on one page and takes a few hours to set up.
What does a simple monthly budget system look like?
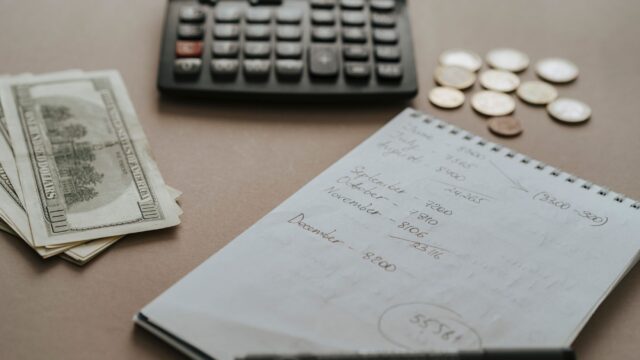
A simple system has one shared spreadsheet, notebook or budgeting app with four parts:
- Income: each take-home paycheck, child support, benefits and any side income.
- Fixed bills: rent or mortgage, insurance, car payments, phone, internet, childcare and loan minimums.
- Flexible spending: groceries, gas, kids’ activities, eating out, clothing and gifts.
- Savings and debt goals: emergency fund, extra debt payments, retirement and planned expenses.
Use take-home pay, after taxes and payroll deductions, because that is the money that reaches your account. If one or both of you earn irregular income, budget from the lowest typical month and treat anything above it as a bonus for savings or debt.
How do you set up the budget the first time?
Set it up in one sitting by looking at what you actually spent, then deciding what you want to spend. A first session usually goes like this:
- Pull the last two or three months of bank and credit card statements.
- Sort each charge into a category, and note bills that come yearly or twice a year (car registration, insurance premiums, school fees, subscriptions).
- Add up monthly income and list fixed bills first.
- Assign amounts to flexible categories based on real past spending, then trim where you both agree.
- Subtract everything from income. If money is left, assign it to savings or debt. If the total is negative, cut flexible categories until it balances.
Giving every dollar a category, even if the category is “savings,” is often called zero-based budgeting. It stops leftover money from disappearing into small purchases.
Which budgeting rule should a family start with?
A common starting point is the 50/30/20 guideline: about 50% of take-home pay for needs, 30% for wants and 20% for savings and extra debt payments. It is a rough target. Families with high rent or childcare costs often spend well over half on needs and can shrink the other two shares to match.
Many couples find a simpler version easier to live with: cover the bills, set a fixed amount for savings on payday, and split what remains into a grocery amount and a weekly spending amount. Pick the method you will actually keep using.
How do you handle bills that don’t come every month?
Bills that come once or twice a year are easiest to handle with sinking funds: divide each yearly cost by 12 and move that amount into savings every month. When the bill arrives, the money is already there.
Typical sinking funds for families include:
- Car insurance, registration and repairs
- Back-to-school supplies and clothes
- Birthdays and holidays (see this guide to making a family Christmas budget before you shop)
- Summer camp or childcare gaps
- Annual subscriptions and memberships
- Vacations, such as a family road trip planned line by line
Many banks let you open several free savings accounts or “buckets” with names, which makes each fund easy to see.
Should couples use joint or separate accounts?
Either setup works as long as both adults can see the shared bills and agree on who pays what. Three common arrangements:
- Fully joint: both paychecks go into one account that pays everything.
- Joint plus personal: each partner moves an agreed amount into a joint account for household bills and keeps the rest.
- Proportional: each partner pays into the joint account in proportion to income, so the higher earner covers a larger share.
Whatever you choose, give each adult a small personal spending amount that needs no explanation. It cuts arguments over coffee and hobbies.
How do you keep the budget going when you’re both busy?
Automation and one short monthly meeting keep a family budget going with little daily effort. Set bills to autopay where possible, and schedule transfers to savings and sinking funds for the day after payday.
Put a 30-minute money meeting on your shared family calendar near the end of each month. Use it to:
- Compare what you planned with what you spent in each category.
- Look ahead at next month: birthdays, school trips, car service, travel.
- Move money between categories to cover any overspending.
- Check progress on the emergency fund and debts.
Groceries are often the largest flexible category, and a weekly plan helps; this week of budget dinners with a shopping list is one way to start.
What are the most common family budget mistakes?
The most common mistakes are forgetting irregular expenses, setting grocery and spending amounts lower than real life allows, and quitting after one bad month. Others include:
- Leaving out small subscriptions that add up over a year.
- Having one partner run the budget alone while the other never sees it.
- Skipping an emergency fund, so every surprise goes on a credit card.
- Paying only minimums on high-interest debt without a plan to pay it down.
A first-month budget is usually wrong somewhere. Adjust the numbers at the monthly meeting; most families have a realistic budget by the third month.
The Consumer Financial Protection Bureau has free budgeting worksheets and guides on debt and saving.
Quick answers
How big should a family emergency fund be?
A widely used target is three to six months of essential expenses. Start with a smaller goal, such as one month of bills, and build from there.
Is a budgeting app better than a spreadsheet?
An app that links to your accounts saves sorting time, while a spreadsheet is free and fully under your control. The best tool is the one both partners will open each month.
How often should couples talk about money?
A short monthly meeting covers most households, with a quick check-in before any large purchase you agreed to discuss together.